ANZ Frequent Flyer Platinum Credit Card Review & Application Guide
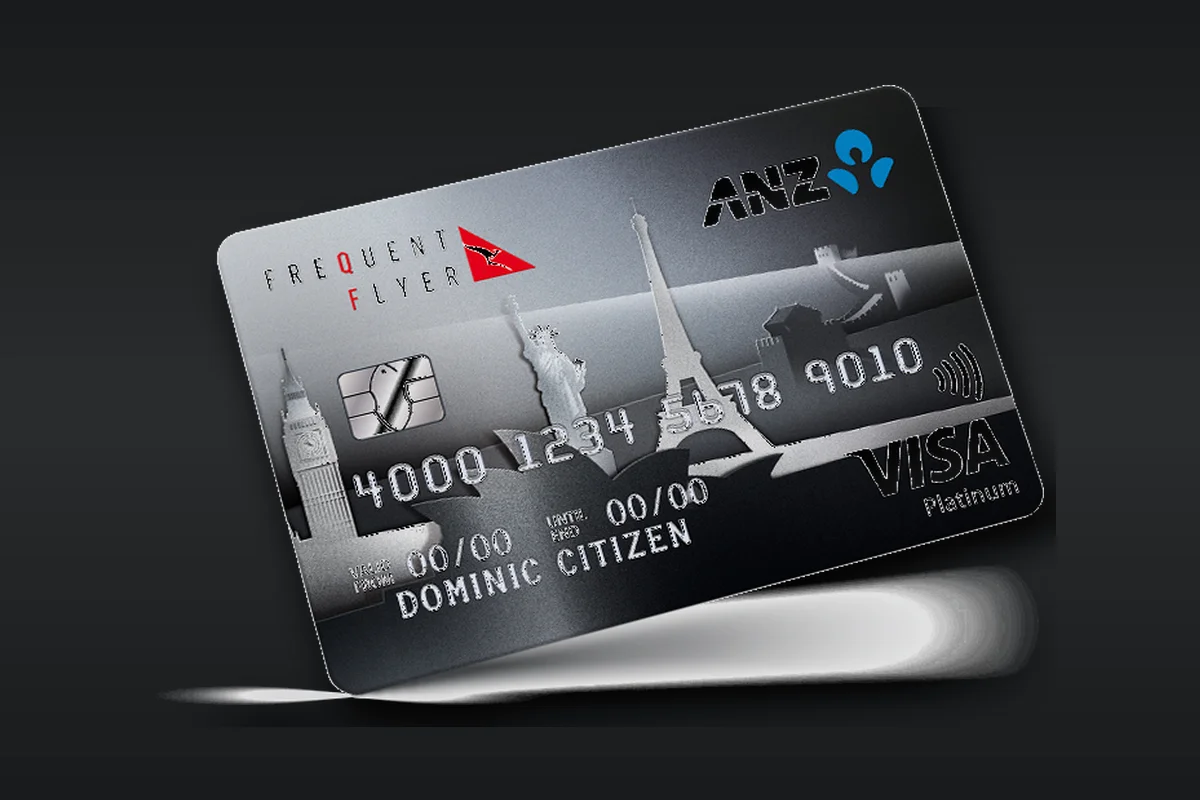
Applying for the ANZ Frequent Flyer Platinum credit card requires a clear understanding of its annual fee structure, interest rates, and eligibility criteria set by Australia and New Zealand Banking Group (ANZ). Before submitting an application through the official ANZ portal, it is essential to evaluate the conditions for earning Qantas Points, the policy terms for complimentary overseas travel insurance, and available interest-free periods on purchases. In the Australian banking and aviation loyalty market, this card remains a reliable choice for cardholders wanting to build their Qantas Points balance.
Compared to basic rewards cards, this platinum option offers high point-earning capabilities paired with valuable travel protections. Cardholders enjoy direct monthly transfers to their Qantas Frequent Flyer account, global emergency support, and robust digital security. In this detailed guide, we have compiled the key technical specifications, eligibility guidelines, and step-by-step application instructions.
Primary Benefits and Platinum Loyalty Perks
The ANZ Frequent Flyer Platinum credit card offers a range of valuable features tailored for everyday spenders and travel enthusiasts:
- Direct Qantas Points Earn: Earn Qantas Points on eligible everyday purchases, automatically credited directly to your linked Qantas Frequent Flyer account each month.
- Bonus Point Spend Acceleration: Earn additional Qantas Points per dollar spent directly on selected Qantas products and flight bookings.
- Complimentary International Travel Insurance: Access overseas medical emergency insurance, luggage cover, and travel delay protection when meeting eligibility spend criteria.
- Complimentary Interstate Flight Inconvenience Cover: Coverage for flight delays or lost luggage on domestic travel within Australia.
- Digital Wallet Integration: Full compatibility with Apple Pay, Google Pay, and Samsung Pay for fast, secure contactless payments.
- ANZ Fraud Shield Protection: Advanced 24/7 account monitoring to protect your card against unauthorized and fraudulent transactions.
Eligibility Requirements and Application Criteria in Australia
To qualify for the ANZ Frequent Flyer Platinum credit card, applicants must satisfy specific personal and financial criteria established by ANZ:
- Age & Residency: Must be at least 18 years of age and hold Australian permanent residency or citizenship.
- Minimum Income Level: Demonstration of a regular, stable gross income meeting ANZ underwriting standards.
- Clean Credit File: A good credit standing free from bankruptcy history, payment defaults, or court judgments.
- Qantas Frequent Flyer Membership: Must hold an active Qantas Frequent Flyer account (or join via the Qantas website).
- Verification Documentation: Submission of valid Australian identification (driver’s licence or passport) and recent proof of income (such as payslips or tax notices).
About Australia and New Zealand Banking Group (ANZ)
ANZ is one of Australia’s major “Big Four” financial institutions, recognized across the Asia-Pacific region for its comprehensive banking network, digital solutions, and customer security infrastructure. Partnering with Qantas Frequent Flyer, ANZ enables cardholders to easily turn daily card usage into flight rewards, upgrades, and merchandise.
Transactions made with the ANZ Frequent Flyer Platinum card are protected by ANZ Fraud Shield and multi-factor authentication protocols. Cardholders can easily manage spending, adjust card controls, and view account statements via the intuitive ANZ App.
Who Is the ANZ Frequent Flyer Platinum Card Best Suited For?
This card is ideal for “everyday spenders and Qantas Frequent Flyer members” who want a reliable major bank card to consistently earn Qantas Points on daily expenses. It is also an excellent fit for “regular overseas travelers” seeking peace of mind with complimentary international travel insurance coverage.
Step-by-Step Guide: How to Apply Online
Submitting an application online is straightforward and takes about 10 to 15 minutes through the secure ANZ portal:
- Visit the official card page: Apply for the ANZ Frequent Flyer Platinum card on the official ANZ site.
- Review the key terms, interest rates, annual fee structure, and eligibility criteria.
- Fill out the online application form with your personal, contact, and employment details.
- Enter your Qantas Frequent Flyer membership number to link your loyalty account directly.
- Upload requested financial documentation (e.g., recent payslips) and submit your application for an instant or conditional decision from ANZ.
Pros and Cons
Evaluating the advantages and disadvantages of this card is crucial for making an informed financial decision.
Pros:
- Automatic Points Crediting: Qantas Points are directly swept into your frequent flyer account every month, eliminating manual transfer requests.
- Welcome Bonus: The ability to earn up to 40,000 bonus Qantas Points offers a strong initial return on everyday spending.
- Accessible Minimum Limit: A $6,000 minimum credit limit makes the card accessible to a broader range of applicants.
- Complimentary Insurances: Features a robust suite of international and domestic travel insurance, plus rental vehicle excess and purchase protection.
- Membership Waiver: The standard $99.50 Qantas Frequent Flyer program joining fee is entirely waived for new members.
Cons:
- Annual Fees: The card carries a significant annual fee of A$295.00, plus $65 per year for each additional cardholder.
- Earning Cliffs: The base earn rate is modest at 0.75 points per dollar and drops severely to 0.5 points once spending exceeds $3,000 in a single statement period.
- No Lounge Access: Unlike some competing platinum cards, this product provides zero complimentary Qantas Club lounge invitations.
- High Interest Rates: The high variable purchase APR will quickly cancel out the value of rewards if you carry a balance.
- Insurance Downgrades: Upcoming policy changes will significantly reduce the international travel cover period and halve the trip cancellation coverage.
Tips for Maximising Value and Card Usage
Follow these essential guidelines to unlock maximum financial value from your ANZ Frequent Flyer Platinum card:
- Clear Your Statement Balance Monthly: Pay 100% of your closing statement balance before the due date to avoid interest charges and preserve the value of your earned points.
- Pay for Travel Expenses on Card: Ensure you prepay your required travel costs using the card to activate your complimentary overseas travel insurance cover before flying.
- Consolidate Routine Household Spend: Use your card for everyday groceries, utility bills, and fuel to maintain a steady monthly flow of Qantas Points.
- Book Qantas Services Directly: Purchase Qantas flights directly with your card to trigger bonus point multipliers.
Fee Structure and Financial Metrics
Key financial metrics and parameters associated with the credit card agreement (Reference data for 2026):
- Annual Card Fee: $295 Annual Fee
- Purchase Interest Rate: 22.49% p.a.
- Balance Transfers: 23.49% p.a.
- Cash Advance & Foreign Currency Fees: 23.49% p.a
Disclaimer / Legal Notice: This article is provided for informational and educational purposes only and does not constitute financial advice. Fees, interest rates, Qantas Points earning rules, insurance policy terms, and card conditions for the ANZ Frequent Flyer Platinum credit card are set directly by Australia and New Zealand Banking Group Limited (ANZ) and Qantas Frequent Flyer and are subject to change. Please review the official Terms and Conditions, Financial Services Guide (FSG), Product Disclosure Statement (PDS), and Target Market Determination (TMD) on the official ANZ website before applying.
About the author

With a background in journalism and advertising, I’m passionate about music, TV series, books, and everything to do with pop culture. I have a strong interest in learning new languages and gaining insight into the traditions and lifestyles of other countries. What I enjoy most in the communications field is writing and producing SEO-focused content that helps make information clear, accessible, and useful for those looking to learn or stay well-informed.